AI-Enabled Crypto Scams: How Fake Relationships Lead to Real Losses
A stranger’s affection, a polished trading dashboard and a sudden “tax” demand can form one carefully engineered crypto fraud. AI helps scammers make identities and conversations convincing, but the money trail is real. Learn how relationship scams work, where legitimate exchanges fit, and what investors and firms should do next.
Atlanta, GA
Oct 6, 2026
The most important feature of a fraudulent crypto investment may not be the trading app. It may be the person who persuades someone to use it.
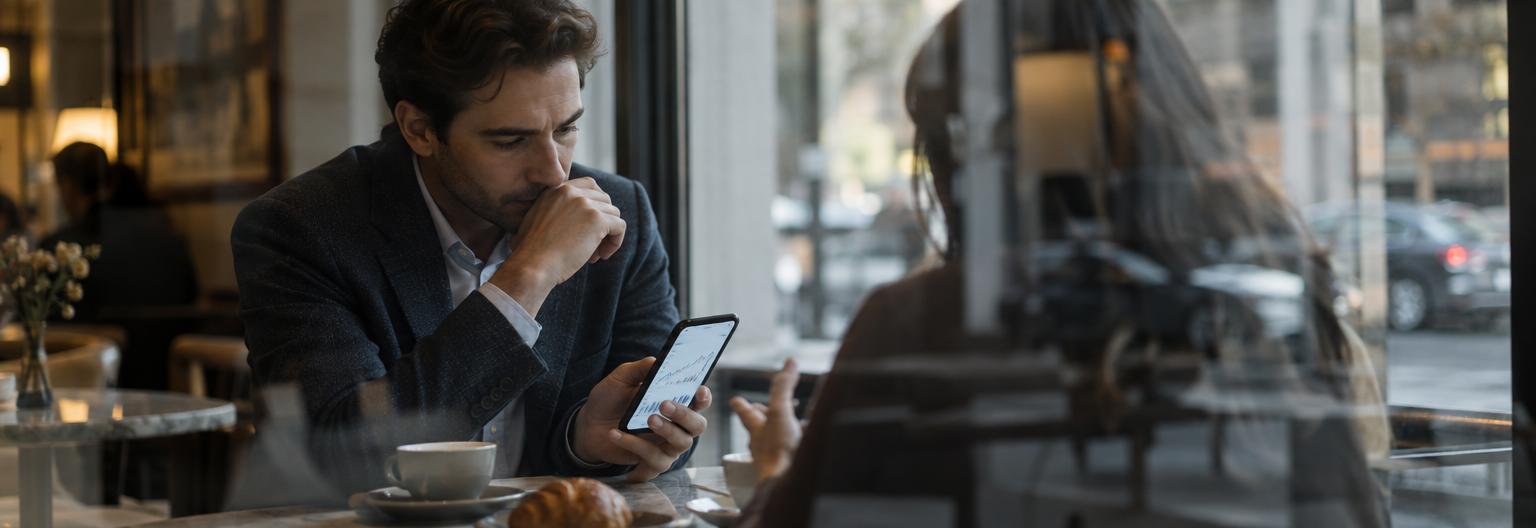
A romantic interest, an online friend or a supposed financial professional can spend weeks building trust before introducing an investment opportunity. By the time money changes hands, the pitch no longer feels like an unsolicited offer. It feels like advice from someone who cares.
That is the mechanism behind relationship investment scams, a threat addressed in Investor.gov’s official guidance. Artificial intelligence can make the deception harder to recognize by helping fraudsters fabricate identities and impersonate people. But the underlying transaction remains painfully simple: a real customer sends real money to an investment that may exist only on a screen.
The relationship is the sales channel
These schemes, sometimes called “pig butchering,” turn personal confidence into financial exposure. A conversation that begins on a dating service, social platform or messaging app gradually shifts toward investing. The contact may claim to have made substantial profits, know a successful trader or have access to an opportunity unavailable to ordinary investors.
The target is directed to a website or app that appears to offer cryptocurrency trading. Its dashboard may show deposits, transactions and growing profits. None of those displays, by themselves, establishes that assets were purchased or that the customer can recover the money.
Some schemes allow an early withdrawal. That apparent success can encourage a larger deposit, making the operation seem more trustworthy precisely when the victim’s exposure is increasing.
The break often comes when the customer tries to withdraw a substantial amount. Suddenly, the platform demands a tax payment, a processing fee or another deposit to unlock the account. The displayed wealth remains visible, but inaccessible. Sending more money does not necessarily bring it any closer.
What AI changes—and what it does not
Synthetic photographs, cloned voices and manipulated video can give a false identity a convincing face and voice. Generated messages can also help sustain attentive, personalized conversations. A video call or polished professional profile is therefore not enough to establish that a person is genuine, qualified or connected to the investment they recommend.
The practical response is independent verification. Investors can check an adviser’s registration and disciplinary history through the Investment Adviser Public Disclosure database and contact their state securities regulator through NASAA’s regulator directory.
Verification needs to go beyond finding a matching name. An impersonator can borrow the identity of a registered professional. Contact information should come from an independently located regulatory record or established business website—not solely from the person making the pitch.
Even a genuine registration does not validate a separate trading platform, guarantee returns or establish who controls a receiving wallet.
A legitimate exchange can be the exit ramp
For consumers, an especially confusing feature is that the first part of the transaction may involve a legitimate business. A customer can buy cryptocurrency through a real exchange and then send it to an address supplied by a fraudster. The exchange’s legitimacy does not extend to the destination.
That distinction also matters for consumer protection. A transfer can be authorized by the account holder while still being induced by deception. Security controls designed to catch stolen passwords or account takeovers may miss a customer acting under the influence of a manufactured relationship.
Customer-support teams may encounter the missing context: someone asking how to send funds to a new platform, describing guaranteed profits or seeking help paying a fee to release an investment balance. Those conversations can offer an opportunity for a calm explanation and referral to a fraud specialist.
Unusual transfers alone are not proof of a scam. Customers have legitimate reasons to move digital assets, and firms should distinguish risk signals from conclusions. The useful question is whether the customer understands who controls the destination and has verified the investment independently.
When the withdrawal becomes another payment demand
A demand for additional money to release supposed profits should prompt an immediate pause. Investors should preserve messages, website addresses, wallet addresses and transaction records, contact the financial service used to send the funds, and report suspected fraud to their state securities regulator and the FBI’s Internet Crime Complaint Center.
Victims should also be cautious about unsolicited recovery services. Someone promising to retrieve lost cryptocurrency for an upfront payment may be attempting a second fraud.
The source description for NASAA’s World Investor Week bulletin gives a publication date of October 5, 2026, but a direct official publication could not be independently verified. Its specific wording, publication status and any claims about the prevalence of AI-enabled fraud therefore remain unconfirmed. The investor-protection guidance above is grounded in the linked official resources; it should not be read as an announcement of new NASAA requirements for crypto businesses.