UK Crypto Sanctions: Why Entity Ownership Matters More Than Platform Names
FCDO HM Treasury OFSIPlatform names can obscure the real sanctions risk: who controls the money. For UK crypto businesses, ownership checks, asset freezes and wallet tracing matter more than brand recognition. This article explains the legal distinctions and practical checks, while flagging why reported October 2026 designations must be verified before firms act.
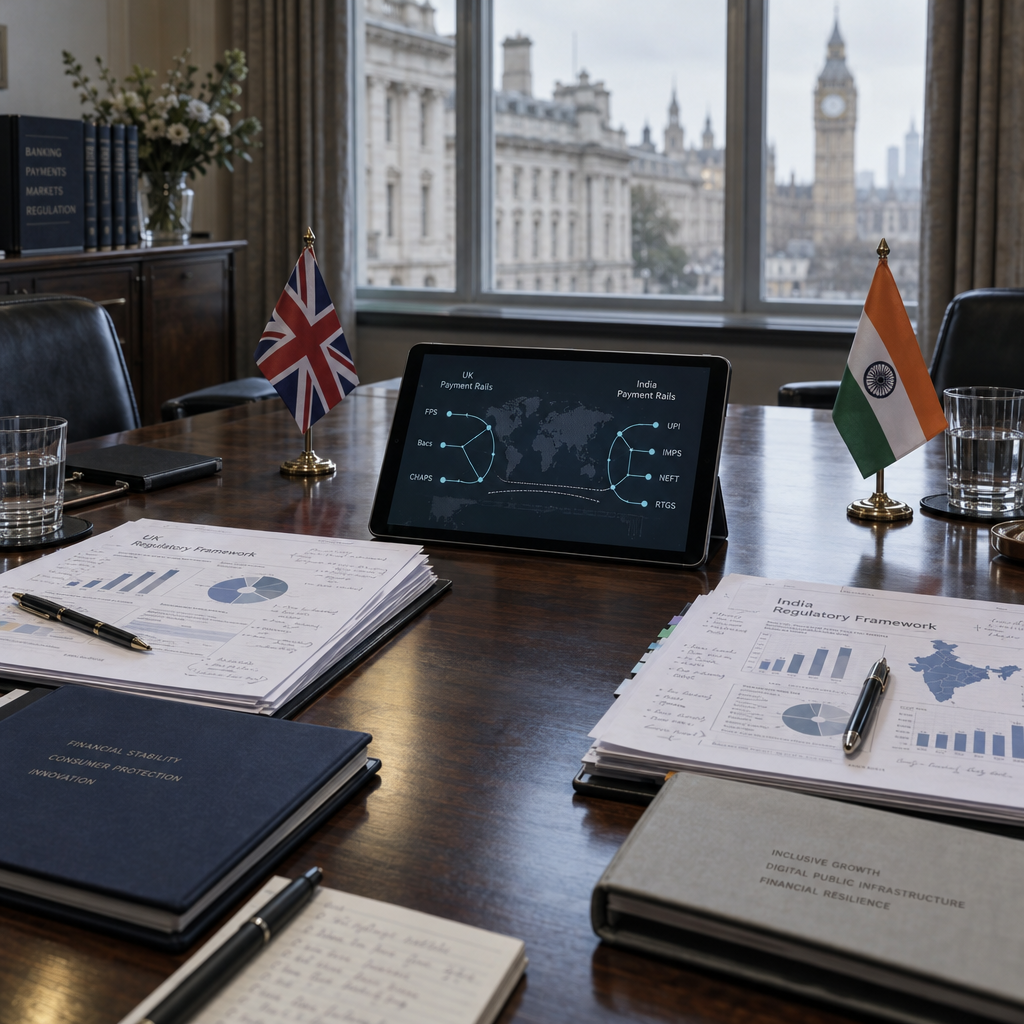
India–UK Financial Markets Dialogue: Digital Finance Talks Do Not Change Crypto Rules
HM Treasury Ministry of Finance (India)India and the UK have opened discussions on digital finance, CBDCs and cross-border financial crime. But crypto firms should not confuse policy talks with new permissions. What does the dialogue actually change, and which compliance obligations remain untouched? A closer look separates diplomatic engagement from genuine regulatory convergence for businesses.
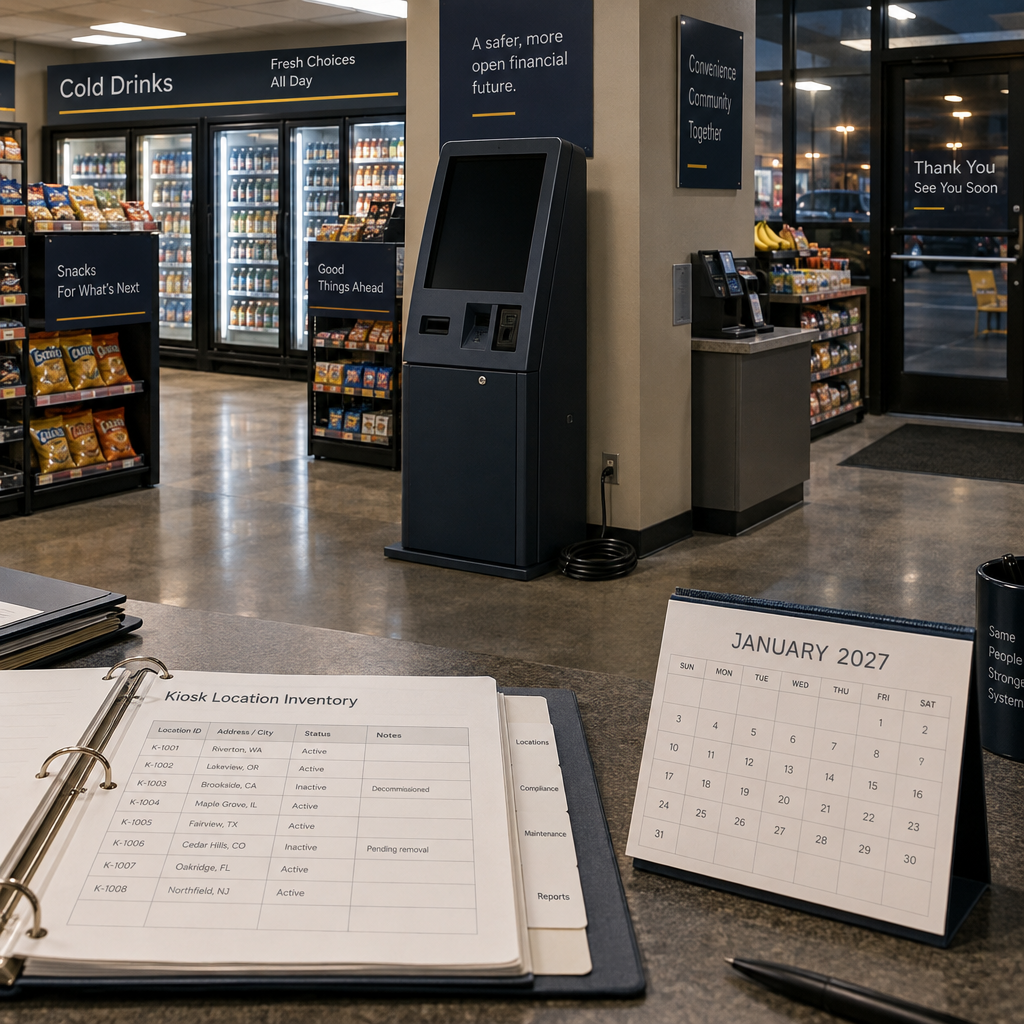
Coinme’s $2.5 Million Settlement Sets January 2027 Crypto Kiosk Shutdown Deadline
CSBS IDFPRA $2.5 million fine is only the start for Coinme. Its settlement with state regulators requires crypto kiosk operations to end in 34 jurisdictions by January 1, 2027, with another $4 million at stake. The bigger challenge: proving that shutting kiosks also comes with meaningful changes to its compliance programme.
UK Tokenisation Roadmap: The FCA and Bank of England’s Market Infrastructure Test
FCAA tokenised security is only the beginning. The UK’s regulators must decide how cash, custody, legal rights and trading fit together before experiments can become real markets. Their roadmap promises direction, not a launch licence. Here are the decisions that will determine whether tokenisation delivers efficiency—or simply adds infrastructure.
FinCEN’s Reported A7 Proposal Raises Hard Questions About Crypto Wallet Attribution
A crypto wallet can reveal where money moved without revealing who controlled it. That gap sits at the heart of FinCEN’s reported A7-related proposal. For banks and compliance teams, the challenge is not simply screening addresses, but proving when a transfer involves a prohibited party—and making that judgment defensibly.
FCA London Crypto Crackdown: When Cash-to-Crypto Trading Requires Registration
FCACash in, crypto out: when does an informal deal become a regulated business? A London crackdown puts that question in focus. See the UK registration rules and the evidence investigators need—and why an unregistered exchange is not automatically a money-laundering case. For crypto dealers, labels may matter less than the operating model.
FCA Crypto Stress Tests: Why Capital Alone Is Not Enough
FCABalance-sheet money does not guarantee customers can get crypto back safely. A bank outage, frozen custodian or blockchain queue can turn stress into a crisis. This article examines why crypto firms’ resilience depends on liquidity, legal rights and operational continuity—and what stress tests must reveal before confidence starts to break.
Bank of England’s Digital Securities Test: From Tokenisation Pilots to Working Markets
Bank of EnglandTokenisation can put securities on a ledger; building a market that trust is harder. The Bank of England’s sandbox offers firms a route to test digital securities, but success depends on legal certainty, liquidity, resilience and coordination. Discover what regulators will expect—and why the next milestone is commercial, not technical.
A7 Network and A7A5: The Wallet Attribution Test for Sanctions Compliance
A wallet can show where tokens travelled, but not who controlled them. In the A7A5 case, that gap can turn a sanctions alert into a difficult investigation. Learn how institutions can test attribution, build SAR narratives and separate confirmed facts from unverified claims—before blockchain clues are mistaken for proof.
UK Stablecoin Draft Separates Payments From Crypto Trading Rules
A stablecoin can pay an invoice, fund a purchase or secure a loan—but UK regulators may treat each use differently. HM Treasury’s draft draws a line around payments, leaving trading, custody and lending regulated. For firms blending services, the question is where payment ends and a regulated service begins.
UK Crypto Authorisation: The FCA Perimeter Tests Firms Need to Apply
Which crypto businesses need FCA permission—and for what, exactly? The answer may hinge less on a token’s name than on its rights, the service offered and the entity delivering it. Explore perimeter tests firms should apply, obligations that remain distinct and why documented analysis matters before an FCA application.
FCA Crypto Authorisation Gateway Sets UK Firms’ Transition Deadline
Application window is coming, but the FCA’s crypto gateway is no rubber stamp. UK firms must work out which permissions they need, prove their controls function in practice and check whether transitional rules let them keep operating. The clock is ticking; preparation, not paperwork alone, will determine who gets through.
Crypto Fraud Recovery: FCA Secures £851,402 in Confiscation Orders
Two convictions, £851,402 in confiscation orders—and a £689,000 question mark. The FCA says recovered money is going back to victims of crypto-investment fraud, but an order to pay is not the same as cash in hand. Here’s what the recovery means, what remains unknown, and why the distinction matters.
Could Stablecoins Become Bank of England Collateral?
Stablecoins may move at digital speed, but can the Bank of England trust one as collateral when markets seize up? A sterling peg is only the beginning: redemption, legal control, reserves and failure plans matter. Explore the hurdles, the risks and why reported policy plans are not an approval yet.