FCA London Crypto Crackdown: When Cash-to-Crypto Trading Requires Registration
Cash in, crypto out: when does an informal deal become a regulated business? A London crackdown puts that question in focus. See the UK registration rules and the evidence investigators need—and why an unregistered exchange is not automatically a money-laundering case. For crypto dealers, labels may matter less than the operating model.
Bucharest, Romania
Oct 5, 2026
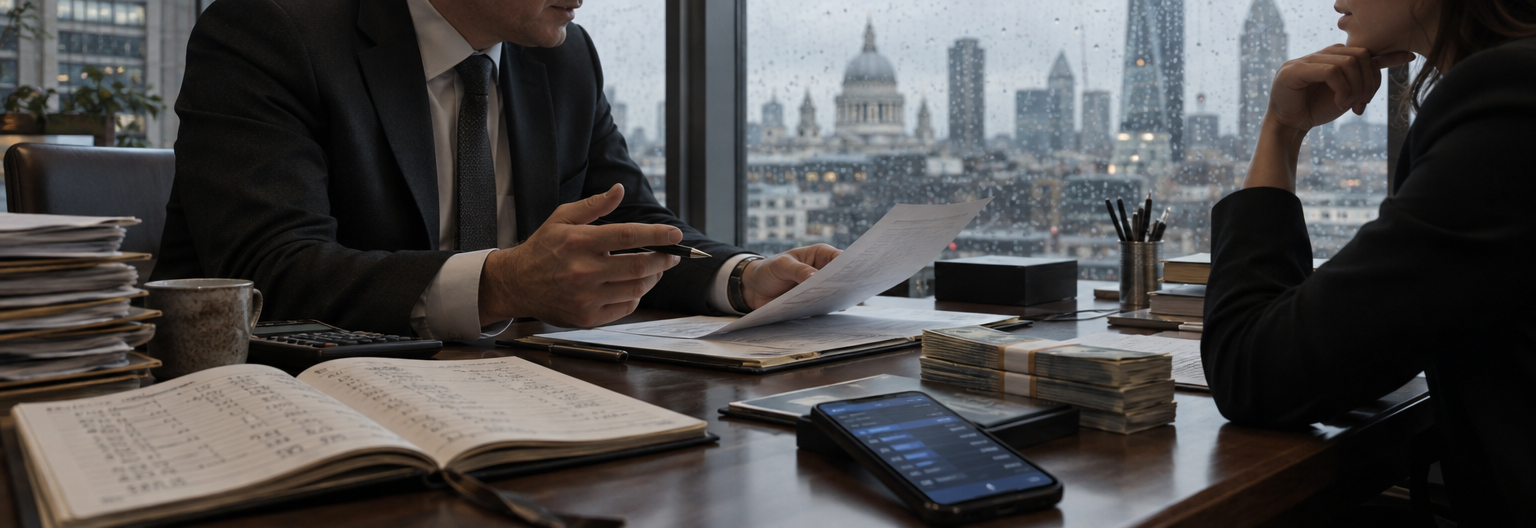
A cash payment, a wallet address and an agreed exchange rate can describe a private cryptocurrency sale. Repeated across a customer network, with organised cash collection and a commercial margin, the same process can describe a cryptoasset exchange business. Under UK anti-money-laundering law, that distinction matters more than whether the operator calls the service “peer-to-peer”.
An account attributed to an FCA announcement on illegal crypto trading describes enforcement action with law-enforcement partners against allegedly unregistered operators across London. The operators are said to have facilitated large-scale cash-to-crypto exchanges through informal trading desks.
The central legal question is not whether cash changed hands. It is whether the operators were conducting a business covered by the UK’s registration requirements—and, if so, whether they did so without the required registration. A separate question is whether any transactions involved criminal property. Those propositions require different evidence.
Where private trading becomes a business
The relevant starting point is the Money Laundering, Terrorist Financing and Transfer of Funds Regulations 2017, as amended to bring specified cryptoasset businesses into the supervisory framework from January 2020.
Regulation 14A defines a cryptoasset exchange provider to include a firm or sole practitioner that, by way of business, exchanges—or arranges or makes arrangements with a view to exchanging—cryptoassets for money, money for cryptoassets, or one cryptoasset for another. The definition also covers operating machines that exchange money for cryptoassets. Custodian wallet providers are separately defined.
That wording reaches beyond a conventional online exchange. An operator does not necessarily need a website, an order book or custody of customers’ cryptoassets to fall within the exchange-provider category. A business arranging transactions between cash buyers and crypto sellers may also be within scope.
The FCA’s guidance on the cryptoasset AML regime explains that businesses carrying on covered activity in the UK must register before starting that activity.
An occasional disposal of someone’s personal holdings does not, without more, establish an exchange business. But trading from an operator’s own inventory is not automatically outside the rules either. A dealer repeatedly selling cryptoassets to customers for a margin may be conducting a business even if every transaction uses the dealer’s own wallets.
Frequency, organisation, advertising, customer relationships and commercial purpose are therefore important evidence. They are not a mechanical checklist or a statutory transaction threshold. “Peer-to-peer” describes how counterparties transact; it does not settle their regulatory status.
What the evidence would need to establish
In a cash-to-crypto investigation, the trading operation must be reconstructed before its legal character can be assessed.
Messages advertising rates, customer instructions, spreadsheets, receipts and commission records could show whether an operator offered a continuing service rather than making isolated private trades. Wallet records and exchange-account histories could help establish how cryptocurrency was sourced and delivered. Evidence of staff or agents collecting cash could reveal an organised operation, although each participant’s role would need to be assessed separately.
The settlement chain is particularly important. The person receiving cash may not control the wallet that sends the cryptocurrency. A third party may supply liquidity, while another person communicates with the buyer. Splitting those functions does not necessarily remove the business from the registration perimeter, but investigators still need evidence connecting the participants and their activities.
Blockchain analysis can identify transfers and relationships between addresses. It cannot, on its own, prove who handed over banknotes, who controlled an address at a particular moment, or what a participant knew about the source of funds. Those conclusions ordinarily require corroboration from communications, account information, devices, financial records or witness evidence.
This is also where registration offences and money laundering must remain distinct. Operating without required registration does not itself establish that every customer’s funds were criminal proceeds. Conversely, registration is not a defence to handling criminal property. Any laundering allegation requires evidence addressing the elements of the particular offence.
Cash raises questions, not conclusions
Cash-to-crypto services create practical financial-crime risks because the cash side of a transaction may leave a limited documentary trail. A blockchain transfer can be visible while the provenance of the money used to buy it remains obscure.
For an in-scope business, the response is risk-based customer due diligence, appropriate monitoring and records that connect the customer, the payment and the cryptoasset transfer. Unexplained third-party cash deliveries, inconsistent identity information or activity structured to evade checks may warrant further investigation. They are indicators to assess, not findings of criminality.
Suspicious activity reporting is a separate obligation where the applicable legal conditions are met. Registering with the FCA does not replace that assessment, and submitting a report does not cure an unregistered business model.
Registration is not a general crypto licence
FCA registration under the money-laundering regulations is a financial-crime supervisory requirement. It is not comprehensive approval of a firm’s products, financial soundness or conduct, and it does not supply permissions required under other legislation. The FCA’s cryptoasset information distinguishes its responsibilities across the relevant regimes.
For legitimate OTC dealers and exchanges, the reported London action points to a concrete compliance task: examine what the business actually does. Referral contracts, pricing arrangements, cash-collection procedures and wallet settlement flows may reveal regulated activity that an informal label conceals.
For investigators, the corresponding task is evidential. Establish the service, identify the people operating it, trace the exchange flows and test the registration position. Any allegation concerning criminal funds must then be proved on its own terms. Strong enforcement depends on keeping those questions separate—not treating cryptocurrency, cash or informality as substitutes for proof.
Source and verification note: The supplied account dates the linked FCA announcement to 10 September 2026. The release and its case-specific details have not been independently verified. Locations, searches, arrests, seizures, charges and the procedural status of any investigation therefore remain unconfirmed. The legal analysis above draws on the linked legislation and FCA guidance; allegations are not findings of liability.