Bank of England’s Digital Securities Test: From Tokenisation Pilots to Working Markets
Tokenisation can put securities on a ledger; building a market that trust is harder. The Bank of England’s sandbox offers firms a route to test digital securities, but success depends on legal certainty, liquidity, resilience and coordination. Discover what regulators will expect—and why the next milestone is commercial, not technical.
London, England
Oct 5, 2026
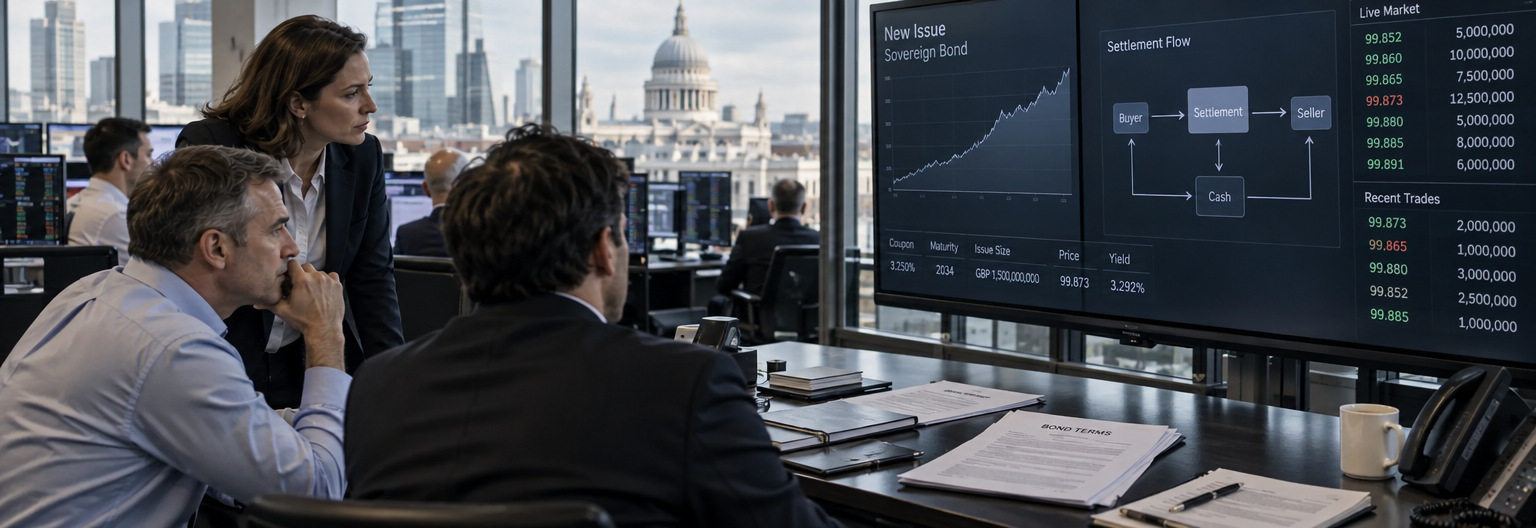
A tokenised bond can be issued successfully without creating a successful bond market. That distinction is becoming central to the debate over digital finance: demonstrating that a ledger works is one task; persuading institutions to trade, fund and settle transactions through it is another.
The supervisory approach attributed to Sasha Mills, the Bank of England’s executive director for financial market infrastructure, addresses that gap. According to the supplied account of her keynote dated 1 October 2026 at the Hogan Lovells and Global Digital Finance Digital Assets Summit, the next test for digital securities is commercial viability, not another technical demonstration.
The account describes five priorities: outcome-focused regulation; support for testing and scaling; clearer regulatory timelines and approval gateways; industry coordination; and cooperation with overseas regulators. Taken together, they point towards a practical question for firms: what evidence will turn a promising prototype into infrastructure that supervisors, investors and counterparties can trust?
What the sandbox permits—and what it does not
The most concrete mechanism is the Digital Securities Sandbox, operated jointly by the Bank and the Financial Conduct Authority. Its legal foundation is the Financial Services and Markets Act 2023 (Digital Securities Sandbox) Regulations 2023.
The sandbox allows eligible firms to develop securities-market infrastructure using new technology within a modified regulatory framework. Its significance is not simply that firms can experiment. It provides a supervised route towards conducting real market activity, subject to approval, conditions and limits.
That makes it different from both a laboratory exercise and an unrestricted commercial licence. Entry does not give a firm permission to undertake every activity in its business plan. Nor does it remove obligations outside the sandbox’s scope or guarantee a permanent route into the ordinary regulatory framework.
The distinction between digital securities and cryptoassets is equally important. This is a framework for securities-market infrastructure, not a general authorisation scheme for cryptocurrency businesses. Putting a financial instrument on a distributed ledger does not, by itself, change the legal rights it represents or eliminate the need to identify which regulatory requirements apply.
For applicants, the commercially important questions are therefore specific: which functions can the firm perform, under which permissions, at what volume, and with what evidence required before it can expand?
Clearer gateways could make those questions easier to answer. But a published process is only useful if firms can understand the standards at each stage and obtain sufficiently timely supervisory feedback to plan investment.
Atomic settlement is not the whole business case
Tokenisation promises more than a new recordkeeping system. Shared ledgers may reduce reconciliation, while programmable processes can automate parts of issuance and asset servicing. Atomic settlement can make the transfer of securities and payment conditional on one another, reducing the risk that one party delivers while the other does not.
Those benefits depend on the surrounding arrangements. The payment asset must be dependable. Participants need enforceable rights, reliable custody and clarity about when settlement becomes final. Systems must also accommodate mistakes, outages and disputed transactions.
Atomic settlement can change liquidity needs as well as reduce settlement risk. A design requiring participants to have cash and securities available for each transaction may impose funding demands that differ from arrangements using netting. Faster settlement is therefore not automatically cheaper settlement; the answer depends on the market and its operating model.
The strongest commercial case will explain not only what the technology automates, but which costs it removes and which new dependencies it introduces.
The problem no platform can solve alone
A functioning market needs counterparties. An efficient platform with few participants may offer less useful liquidity than an older system with deep institutional participation.
This is where the reported emphasis on industry coordination matters. Firms can make sensible individual decisions about ledger design, identity checks and messaging formats while collectively creating a fragmented market. If assets and cash cannot move reliably between systems, tokenisation may replace existing silos rather than remove them.
Interoperability is not purely a technical question. Connecting platforms also requires agreement on legal responsibility, access rules, data handling and the treatment of failed transactions. A bridge between ledgers is of limited value if participants cannot establish who bears the loss when it breaks.
The Bank can help convene those discussions. It cannot guarantee that institutions will adopt a standard or that a platform will attract demand.
For smaller technology companies, proportionality will be consequential. A pathway that is clear but assumes every applicant has the resources of an established market-infrastructure group could entrench incumbents. Conversely, lowering expectations for resilience or safeguarding would undermine the confidence new entrants need. The workable balance is staged scrutiny tied to the activity and risk, rather than to a firm’s pedigree.
Legal certainty must travel with the asset
Cross-border cooperation addresses another limit to technical progress. A ledger may operate across jurisdictions, but securities law, insolvency rules and the treatment of custody do not become uniform simply because transactions share a network.
Issuers and operators need to establish what a token represents, how ownership transfers and which records prevail if systems disagree. Investors need to know whether their rights remain enforceable when an intermediary or infrastructure provider fails.
Supervisory alignment can reduce incompatible expectations. It cannot substitute for that legal analysis, nor make approval in one country sufficient in another.
The direction described in Mills’s keynote is consequently more demanding than an invitation to run pilots. It asks firms to connect technical capability with an investable operating model: credible governance, resilient systems, enforceable rights, usable liquidity and a defined regulatory route.
The meaningful measure of progress will not be how many securities can be represented as tokens. It will be whether those securities can circulate through markets that businesses and investors have sound reasons to use.
Source note: The description of Mills’s keynote is based on the supplied summary and linked speech address; the speech text has not been independently verified. The sandbox’s statutory basis is linked above.