Blockchain Transaction Volume Is Not the Same as Economic Activity
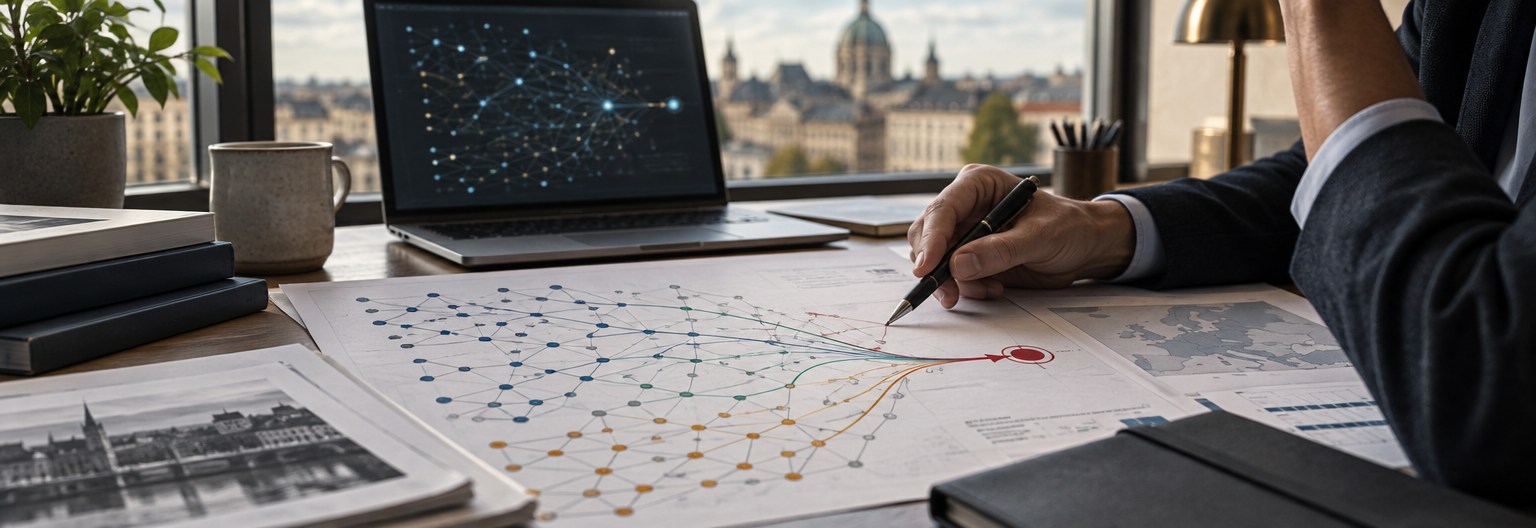
Blockchain ledgers reveal every movement, but not every movement’s meaning. Change outputs, smart-contract routing and cross-chain bridges can turn one economic action into a flurry of records. A DNB paper asks how analysts can separate technical activity from genuine payments, adoption and risk—and why that distinction matters to regulators.
Berlin, Germany
Oct 5, 2026
A wallet sends funds. A smart contract executes a swap. A bridge moves tokens between networks. Each action leaves a blockchain record—but those records do not necessarily represent three payments, three users or three independent pieces of economic activity.
That distinction matters whenever transaction volumes are used to measure crypto adoption, compare stablecoin networks or assess financial risk. The ledger can establish that something happened under a protocol’s rules. Establishing what it meant economically requires another layer of analysis.
De Nederlandsche Bank’s Working Paper No. 870, “Hidden by complexity? Measuring stablecoin, crypto and decentralised finance ecosystems” examines that gap. According to the supplied description, the study draws on approximately 100 billion blockchain records collected through Project Mercurius across Bitcoin, Ethereum and Tron.
Its central lesson is not that blockchain data are unreliable. It is that a reliable record of a technical event is not automatically a reliable measure of its economic purpose.
Bitcoin: why change can inflate a transfer
Bitcoin does not work like a bank account from which an exact amount is simply deducted. A transaction spends previously received outputs and creates new ones. When the inputs exceed the amount being paid plus the transaction fee, the remainder ordinarily returns to the sender as change.
Consider a simplified example. A user spends an output worth 1 BTC to pay someone 0.1 BTC. Ignoring the fee, the transaction creates a 0.1 BTC payment output and a 0.9 BTC change output.
Adding all outputs produces a transaction value of roughly 1 BTC. Counting only the payment produces 0.1 BTC. Both calculations use the same ledger, but they answer different questions.
The DNB paper’s supplied summary reports that Bitcoin transaction-value estimates can differ by as much as sixfold depending on how outputs and change addresses are treated. That is a finding about sensitivity to methodology—not a universal correction factor for Bitcoin volumes.
Removing change also requires care. An address is not a person, and the blockchain does not explicitly label every output as “payment” or “change.” Analysts often rely on heuristics whose accuracy depends on wallet behaviour and transaction structure.
A better estimate therefore explains both what was excluded and how those exclusions were inferred.
Ethereum: one transaction, several economic steps
Ethereum presents a different problem. A single transaction can call a smart contract that interacts with other contracts, transfers tokens and emits multiple event logs.
A user swapping one token for another might trigger a router, several liquidity pools and multiple token transfers. Those transfers matter technically: they explain how the swap was executed. But adding every transfer’s value may count intermediate movements as though each were a separate end-user trade.
The reverse problem also exists. A single transaction can bundle multiple operations, making transaction count a poor guide to the number or significance of actions performed.
Analysts need to distinguish among transactions, contract calls, token-transfer events and the economic activities those records support. These are related units, not interchangeable ones.
Classification makes blockchain data more useful. It also introduces assumptions. Identifying a swap is not the same as knowing why the user made it, whether the participating addresses have a common owner or whether the activity reflects independent demand.
Stablecoins: transfers are not necessarily payments
Stablecoins illustrate why purpose matters as much as volume.
A transfer might settle an invoice, fund an exchange account, move collateral into a lending protocol or shift funds between wallets controlled by the same person. All can produce visible token movements. Only some represent payments between independent parties.
Cross-chain activity adds another complication. Depending on the bridge’s design, moving an asset between networks can involve locking and releasing tokens, or burning and minting them. Summing records across networks without identifying those relationships can count multiple legs of one movement.
That does not make the records meaningless. It means the measurement needs a defined question. Gross token movement, trading settlement and estimated payment activity are different statistics, even when all are presented as “stablecoin volume.”
Better metrics begin with narrower claims
The paper’s proposed approach, as described in the supplied material, is to use granular, data-bounded estimates: classify technical activity, separate relevant categories and make the assumptions connecting ledger events to economic meaning explicit.
For anyone publishing or relying on a volume figure, five questions follow:
- What is being counted? Transactions, outputs, token transfers or classified economic actions?
- What is removed? Change, self-transfers, intermediate routing or other internal movements?
- How is ownership inferred? Different addresses do not necessarily mean different owners.
- How are networks combined? Are bridge movements identified, and are equivalent measures being compared?
- How sensitive is the result? Would another reasonable classification materially change the estimate?
Data providers can help by publishing coverage notes, explaining their filters and flagging methodology changes. Where ownership or purpose remains uncertain, ranges or alternative estimates may be more informative than one precise-looking total.
Measurement should guide regulation—not substitute for it
For supervisors, large on-chain volumes can identify areas worth examining. They do not, on their own, establish payment adoption, financial exposure or the existence of a conventional intermediary.
Those questions require additional evidence: who controls assets, who can alter a protocol, where obligations arise and which participants can intervene. A contract routing tokens is not necessarily performing the same economic role as a business holding customer funds.
Equally, technical complexity does not make risk disappear. It makes accurate classification more important.
Blockchain transparency offers an unusually detailed foundation for financial analysis. The opportunity is to build measurements that exploit that detail without confusing visibility with understanding. The ledger records the transfer. Explaining what it means remains the analyst’s job.
Source note: This article uses the supplied description of the DNB paper, which lists a publication date of 1 October 2026. The paper, publication date and reported findings have not been independently verified.