ESMA’s MiCA Stablecoin Guidance Sets Out a Managed Exit for EU Crypto Firms
Stopping new stablecoin purchases is only half the job. ESMA’s MiCA guidance also demands an orderly exit for existing holders. Explore the verified 2025 timetable, why delisting alone may not deliver compliance, and how EU crypto firms must separate prohibited distribution from legitimate sales, conversions, custody and transfers across borders.
Paris, France
Oct 9, 2026
The European Securities and Markets Authority has made clear that crypto firms cannot use an orderly transition as a reason to keep offering non-compliant stablecoins indefinitely. Its verified guidance calls for restrictions on services that make such tokens available to EU investors, while allowing a limited window for customers to sell or convert existing holdings.
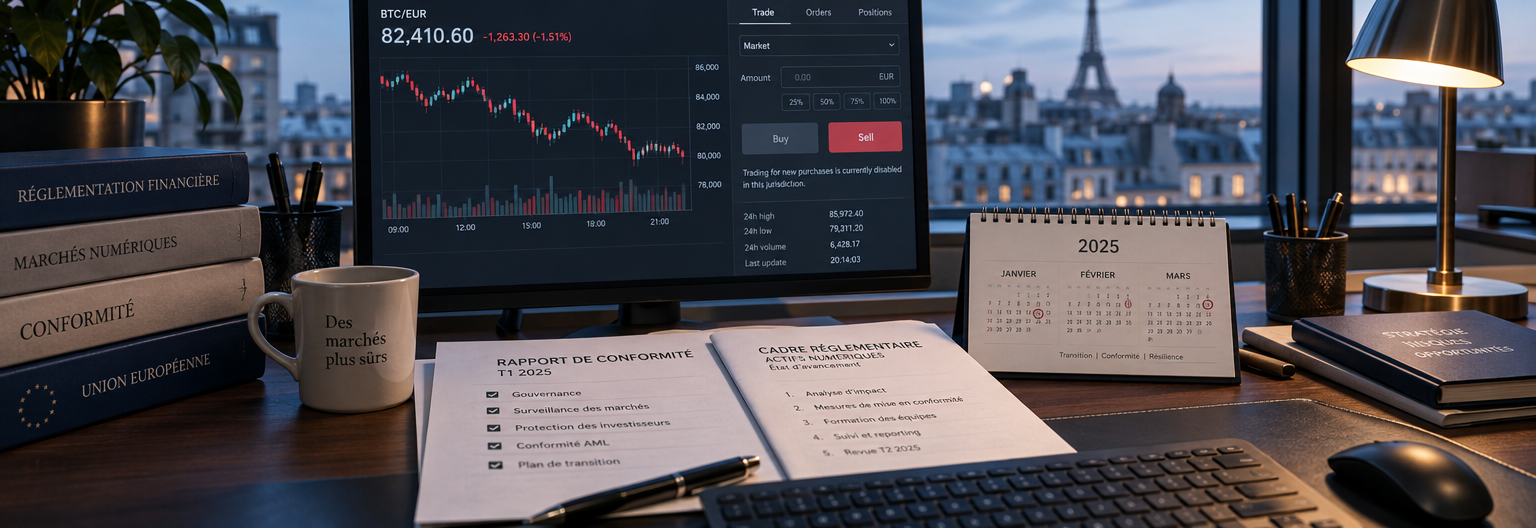
In its January 17, 2025 announcement and accompanying supervisory statement, ESMA asked national competent authorities to ensure that crypto-asset service providers brought relevant services into compliance with the Markets in Crypto-Assets Regulation, known as MiCA, no later than the end of the first quarter of 2025. The statement provided for restrictions by the end of January, with a longer, sell-only period available until the end of March to help investors exit affected positions.
The distinction between those stages matters. Preventing new purchases addresses the continued distribution of a non-compliant token; allowing sales or conversions helps customers resolve holdings they already own. A managed exit is therefore not equivalent to continued ordinary trading.
What MiCA requires
The legal foundation is the Markets in Crypto-Assets Regulation, whose provisions governing asset-referenced tokens and e-money tokens became applicable on June 30, 2024. Most of the remaining regulation, including its framework for crypto-asset service providers, became applicable on December 30, 2024.
MiCA distinguishes between two categories commonly grouped together as stablecoins. E-money tokens seek to maintain a stable value by reference to one official currency. Asset-referenced tokens refer to another value or right, or a combination of them, potentially including several currencies. The requirements governing their issuance and distribution differ, making the classification of each token an essential first step.
A token’s popularity, liquidity or availability outside Europe does not establish that it meets MiCA’s requirements. Nor does authorisation of the exchange or broker handling it automatically resolve the regulatory position of its issuer. Firms must assess both their own permissions and the conditions under which the particular token can be offered or admitted to trading in the EU.
ESMA’s statement sought to coordinate how national supervisors apply those requirements. Its transition timetable was a supervisory implementation measure, not an amendment to MiCA or a new legislative exemption for stablecoins.
More than a delisting exercise
For exchanges and brokers, removing an affected trading pair is the most visible response. But the legal question is broader: does another service still allow an EU customer to acquire the same token?
Execution services, exchange functions and other distribution arrangements can require attention even after a trading venue removes a listing. Firms need to examine how their products operate together, rather than assume that a change to one screen or order book closes every route to a purchase.
That does not mean every service involving an existing holding is automatically prohibited. Custody and transfers raise different questions from offering a token to the public or admitting it to trading. Treating those functions as interchangeable risks obstructing the very withdrawals or disposals needed for an orderly exit.
The operational challenge is to separate acquisition from resolution. A sell-only arrangement must genuinely prevent purchases, including transactions that recreate exposure through another product. At the same time, customers need clear information about which transactions remain available, when restrictions take effect and how they can dispose of or move their assets.
Consistency is the supervisory test
A coordinated European timetable can reduce the risk of firms receiving materially different instructions across member states. Its usefulness, however, depends on national authorities applying a sufficiently consistent interpretation of the services affected and the transactions permitted during an exit.
For businesses operating across several jurisdictions, uncertainty can be as consequential as the restriction itself. Token assessments, changes to trading systems, customer notifications and arrangements with counterparties all take time. Clear supervisory instructions make those changes easier to implement without unnecessary disruption.
The underlying policy is straightforward: MiCA-compliant distribution should not be undermined by indefinite transitional access to non-compliant products. The harder task is delivering that policy without confusing a ban on new acquisition with an obligation to strand customers’ existing assets.
Verification note: The October 8, 2026 opinion and January 8, 2027 deadline described in the supplied material could not be independently verified. The dates and measures reported above refer to ESMA’s January 17, 2025 supervisory statement, linked above; they should not be read as confirmation of a later opinion.