IBIT Options Limits and Bitcoin Futures: Why the Benchmark Matters
An IBIT options ceiling is only as useful as the exposure it captures. Comparing it with CME bitcoin futures can illuminate capacity, but not erase risk or rewrite compliance obligations. Explore why delta, aggregation and exemptions matter, and why the cited proposal’s unverified details demand scrutiny before desks change controls.
New York, NY
Oct 9, 2026
For firms trading options on the iShares Bitcoin Trust ETF, the important question is not simply how many contracts an exchange permits. It is how much bitcoin-linked exposure those contracts represent—and whether the limit leaves enough capacity for market makers to quote and institutional investors to hedge without allowing excessive concentration.
A delta-based comparison with CME bitcoin futures could help answer that question. But two distinctions are essential: using delta to justify an options position limit is not necessarily the same as requiring traders to comply with a continuously recalculated delta limit, and using futures as a benchmark does not make ETF options and futures interchangeable.
Those distinctions are central to evaluating the proposed IEX changes identified under SEC Release No. 34-106575. The cited materials are an SEC rule-filing document and a Federal Register notice dated October 7, 2026. The proposal is described as addressing position and exercise limits for IBIT options, alongside listing and withdrawal standards for options on crypto-asset trust shares. Its specific numerical limits and compliance mechanics require confirmation from the operative rule text.
A benchmark is not necessarily the rule traders follow
Position limits constrain the size of an options position under an exchange’s aggregation rules. Exercise limits separately constrain the number of contracts that may be exercised over a specified period. Both can restrict a trading firm’s capacity, but neither should be confused with an internal risk limit or a measure of potential loss.
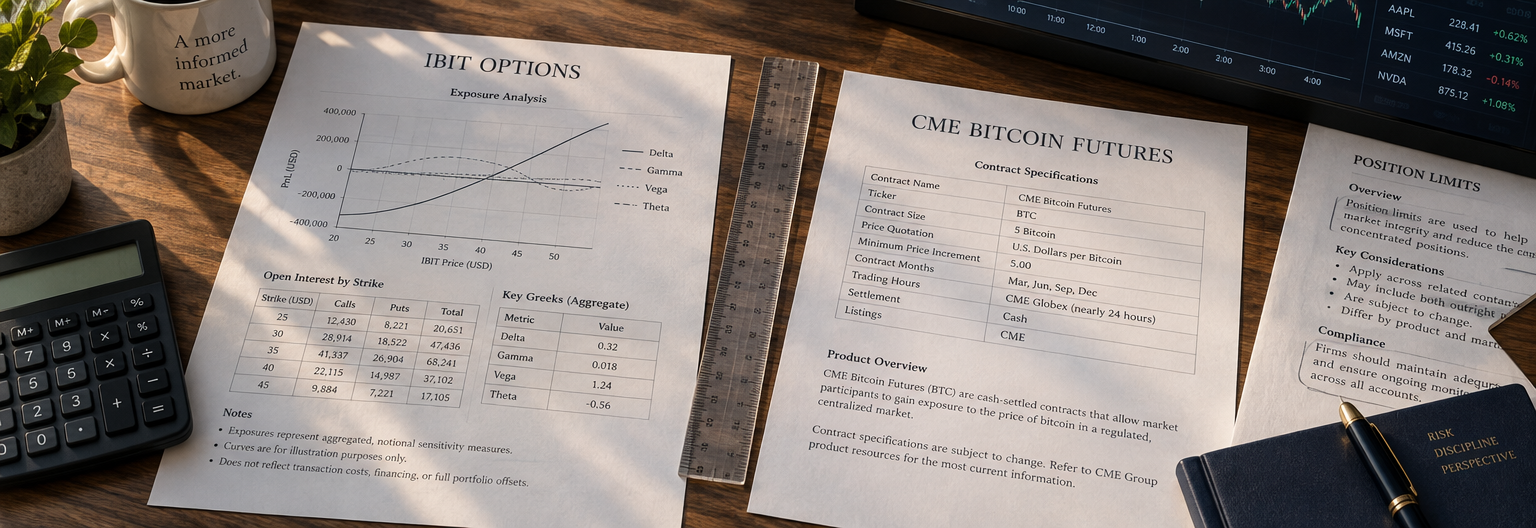
Delta measures an option’s sensitivity to a small move in the underlying share price. A standard, unadjusted ETF option generally represents 100 shares. At a delta of 0.50, one such contract has approximately the immediate price sensitivity of 50 shares; at a delta of 0.10, it has approximately the sensitivity of 10 shares. The same contract count can therefore represent substantially different exposure.
That makes delta useful when an exchange explains why a particular contract ceiling is appropriate. It can translate an assumed options position into share-equivalent exposure and support a comparison with another market’s limits.
It does not follow that the exchange will permit every portfolio with the same net delta, recognize every hedge as an offset, or recalculate compliance whenever an option’s delta changes. A fixed contract limit supported by a delta-based economic analysis remains a fixed contract limit unless the rule expressly provides otherwise.
For trading desks, that is the difference between a justification and an operating requirement. A genuinely delta-adjusted limit would require monitoring changing sensitivities as prices, volatility and time to expiration move. A fixed ceiling would instead require contract counting and aggregation under the applicable rules, even if delta helped establish the ceiling.
Where the CME comparison helps—and where it stops
CME bitcoin futures provide an established reference for bitcoin derivatives exposure. A standard CME bitcoin futures contract represents five bitcoin, while a Micro Bitcoin futures contract represents one-tenth of a bitcoin. A meaningful comparison therefore needs to identify the contract and the particular limit being used, rather than refer broadly to “CME limits.”
Translating IBIT options into comparable bitcoin exposure also requires more than an option count. Relevant inputs include the option multiplier, delta and the bitcoin exposure represented by the underlying trust shares. Those assumptions determine how persuasive the resulting comparison is.
Even a careful conversion captures only part of the risk. IBIT options are options on exchange-traded trust shares; CME bitcoin futures are cash-settled derivatives tied to a bitcoin reference rate. Their financing, settlement, liquidity and trading arrangements differ. A hedge between the two can leave basis risk, execution risk and mismatches in trading hours.
Delta also changes. Two portfolios with similar current sensitivity can react differently to a larger market move because of their strikes, expirations and gamma—the rate at which delta changes. A futures-based comparison can make a proposed ceiling easier to understand economically without demonstrating that the portfolios are equally risky.
Capacity matters, but the details decide who benefits
Higher usable limits can give market makers more room to warehouse customer flow and allow institutions to execute larger hedges. Those are plausible benefits, not automatic outcomes. Quoting capacity also depends on capital, financing, hedge availability and the cost of carrying positions through volatile markets.
Aggregation and exemptions can be just as consequential as the headline ceiling. A firm needs to know which accounts are combined, how positions on the same side of the market are counted and whether qualifying hedged positions receive special treatment. An economic argument based on offsetting exposures does not itself authorize those offsets for compliance.
Listing standards address a different question: which underlying trust products are eligible for options trading and when that eligibility can be withdrawn. A framework covering single-asset and multi-asset crypto trusts should not be read as extending an IBIT-specific position limit to every eligible product. Different underlying portfolios can create different concentration and hedging problems.
If confirmed, an immediately effective exchange filing would also remain distinct from an SEC determination that ETF options and bitcoin futures carry equivalent risks. Immediate effectiveness describes a regulatory procedure, not a guarantee of liquidity, safety or economic equivalence.
The market-structure test is straightforward: does the rule provide enough capacity for competitive quoting and institutional hedging while placing a defensible constraint on concentrated positions? A futures benchmark can strengthen that analysis. The actual limit, aggregation provisions and exemptions determine whether it works on a trading desk.
Source verification note: The cited October 7, 2026 notice and Release No. 34-106575 have not been independently verified. The filing’s existence, effective status, numerical limits and exact use of delta should not be treated as established on the basis of those references alone.