KCEX Investor Alert Raises Canadian Crypto Registration Concerns
A crypto platform’s brand is not its regulatory authorization. The BCSC’s KCEX warning challenges Canadian firms to look beyond marketing and verify the entities, products and permissions behind a trading relationship. Here’s what the alert says, what it does not establish, and where meaningful counterparty diligence should begin before onboarding.
Toronto, ON
Oct 9, 2026
The British Columbia Securities Commission’s warning about KCEX puts a familiar question back at the centre of Canadian crypto regulation: which legal entity is offering the product, and is it authorized to offer it here?
In an investor alert published through the Canadian Securities Administrators, the BCSC says the cryptocurrency trading platform operating at kcex.com is engaging in unregistered securities and derivatives business activities. The regulator states that KCEX is not registered to trade or advise in securities or derivatives in British Columbia or elsewhere in Canada. The notice is dated October 8, 2026, and identifies crypto-asset transactions and derivatives or futures products as the activities of concern.
For firms considering a relationship with the platform, that is a specific regulatory objection to investigate—not merely a general warning about cryptocurrency risk. It also requires careful attribution: the assertion of unregistered activity is the BCSC’s position, and the alert does not set out the underlying evidence or a detailed analysis of individual products.
The issue is authorization, not branding
Canadian securities regulation does not turn solely on whether a business describes itself as an exchange or calls its products digital assets. The relevant questions include the rights a customer acquires, the obligations the platform assumes and whether the business is trading or advising in securities or derivatives.
That distinction matters even for services marketed as ordinary crypto trading. Under Canadian regulators’ approach, a customer’s contractual claim against a platform can bring securities legislation into play even when the underlying crypto asset is not itself a security. Whether customers receive immediate delivery and control of an asset, or instead retain a claim against an intermediary holding it, can be important to that analysis.
Futures and other derivatives introduce a separate set of questions. Their treatment depends on the instrument’s terms, the activity being conducted and the applicable provincial framework. The KCEX alert identifies that product category but does not explain the structure of particular contracts, the use of leverage or the arrangements through which customers obtain access.
The result is a clear registration concern, but not a product-by-product legal determination. The platform’s name, website and descriptions of its services cannot substitute for examining the actual customer agreement and trading arrangements.
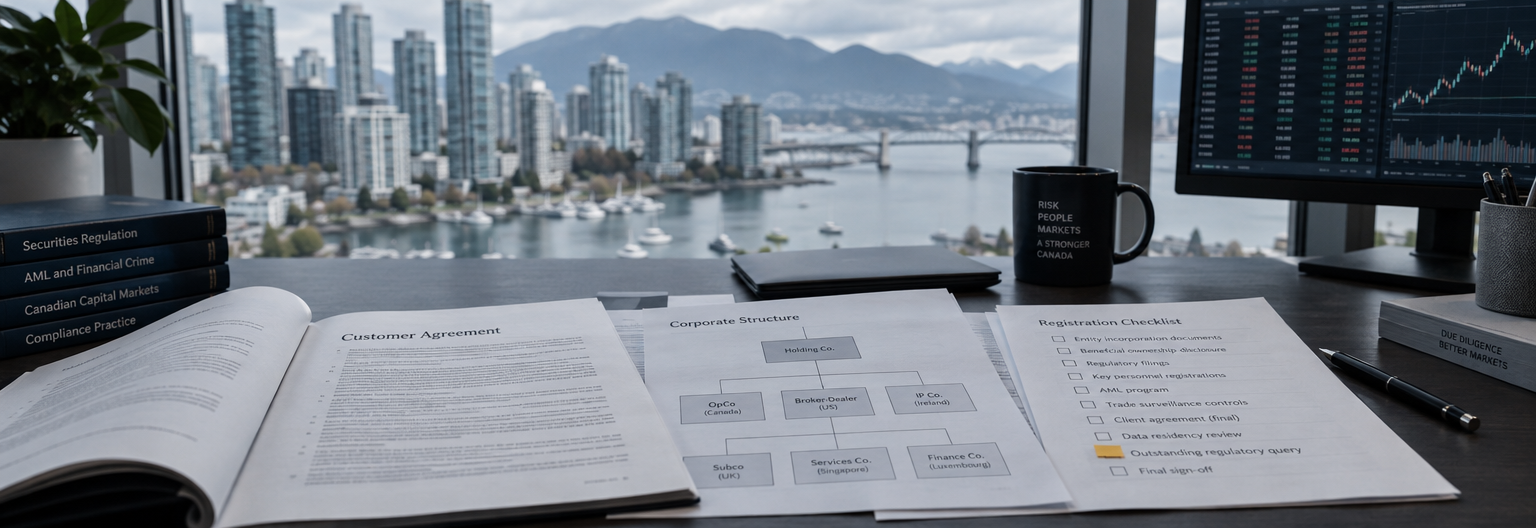
A registration check must follow the legal entity
The CSA National Registration Search is a practical starting point for assessing a platform’s regulatory position. A useful search, however, must go beyond entering a brand name and looking for a matching result.
The entity named in the customer contract should be identified, along with any separate companies responsible for execution, custody or the provision of derivatives. Any registration must then be assessed for its category, jurisdictions, terms and conditions. If a business relies on an exemption or other regulatory relief, the relevant document and its limits need to be examined separately.
Registration held by an affiliate does not necessarily authorize the entity serving the customer. Nor does authorization in another country establish permission to conduct securities or derivatives business in Canada. Those distinctions are particularly important where a platform’s website presents a single brand but its contractual arrangements involve several companies.
The BCSC’s statement is expressly Canada-wide in its description of KCEX’s registration status. That makes the alert relevant beyond British Columbia, while leaving firms responsible for examining the law and permissions applicable to their own activities and relationships.
What changes for counterparties
An investor alert can alter an onboarding decision before any enforcement proceeding reaches a conclusion. A compliance team may reasonably escalate a proposed relationship, seek additional documentation or reconsider an existing exposure after a regulator identifies a named platform as conducting unregistered business. Those are risk-management responses, not obligations imposed on every counterparty by the alert itself.
The most useful review connects the regulatory concern to the actual relationship. Does the firm refer customers to the platform, provide trading access, execute transactions through it or hold assets there? Which entity owes the contractual obligations, and what evidence supports its claimed authority to perform them?
Operational questions belong alongside the registration analysis. A counterparty should understand who controls customer assets, whether those assets are segregated, how withdrawals work and what contractual rights would survive an insolvency. A registration search cannot answer those questions, and the KCEX notice does not purport to resolve them.
The review should also distinguish documentary evidence from representations. A platform’s assurance that it complies with applicable law is less informative than an identifiable registration, exemption or regulatory decision covering the relevant entity and activity.
The boundary of the warning
The public notice does not provide KCEX’s response, establish the terms of every product available to Canadian customers or explain whether further regulatory action has followed. Those gaps limit what can responsibly be concluded about particular transactions. They do not erase the significance of a provincial securities regulator publicly raising a registration concern.
For Canadian compliance teams, the practical consequence is a higher burden of diligence: establish the entity, identify the product, verify the claimed authorization and document what remains unresolved. The alert supplies a reason to ask those questions; it does not supply all the answers.
The KCEX alert is an investor warning, not a court judgment, enforcement order or adjudicated finding of liability. Its date and current status, and any subsequent regulatory action, should be checked against the official record before reliance.