This Week in Canadian Banking: Budget 2026 Sets a Subsidiary Pathway for Bank Stablecoins
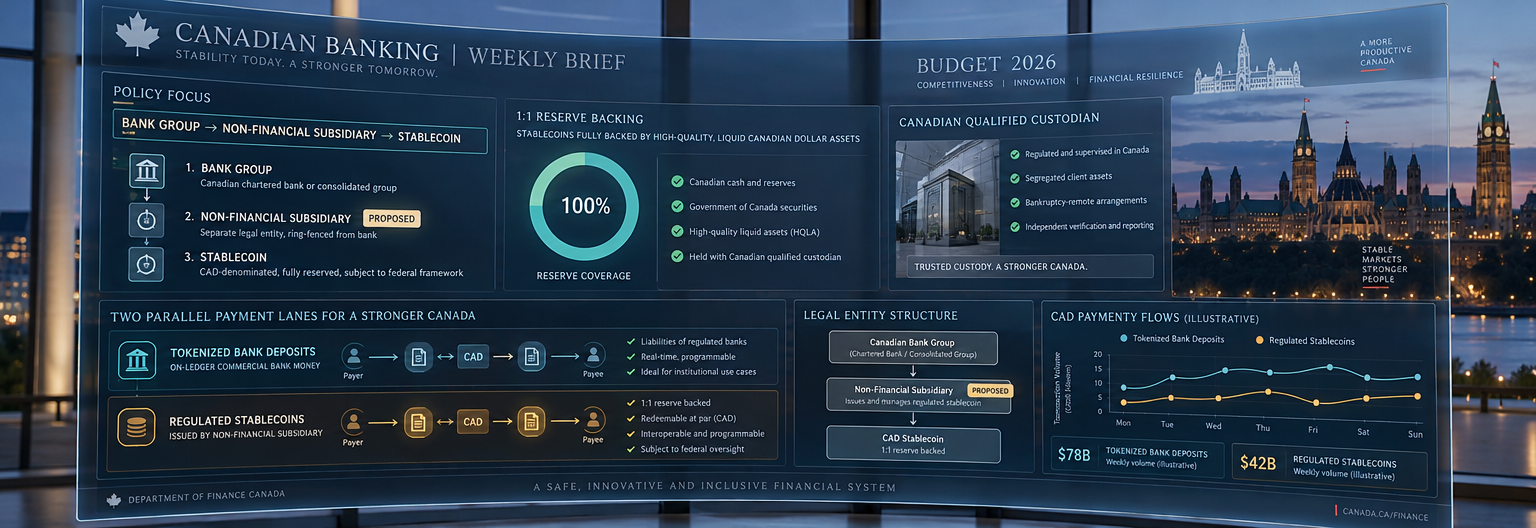
Ottawa’s digital-money framework is becoming more explicit about where innovation belongs inside a banking group. This week’s budget proposals establish a subsidiary route for bank-issued stablecoins, while reserve rules and tokenized-deposit initiatives show how Canada’s next payment infrastructure could develop along two distinct, closely watched tracks with different legal foundations.
Ottawa, ON
Nov 8, 2026
This week’s overview
The first week of November brought a consequential package for Canadian banks exploring digital money. Budget 2026 proposes a dedicated subsidiary pathway for stablecoin issuance, while related changes address the boundary between issuing a payment token and taking a bank deposit.
Alongside that legislative agenda, the Bank of Canada’s developing stablecoin supervisory framework points to a potential role for banks as reserve custodians. The Big Six banks’ joint work on tokenized Canadian-dollar deposits adds a separate, complementary track.
From Ottawa, the common thread is clearer institutional architecture: give digital payments room to develop, but specify which entity owes the customer money, which rules apply and where the backing assets sit.
1. Budget 2026: a separate entity for bank stablecoins
The budget proposes requiring federally regulated financial institutions that issue stablecoins to do so through dedicated non-financial subsidiaries governed by the federal Stablecoin Act. For banking groups such as RBC, TD, BMO and Scotiabank, that establishes a defined route into issuance rather than treating a stablecoin as another product issued directly by the bank.
The distinction matters because a familiar banking brand can obscure an unfamiliar legal arrangement. A customer may recognize the parent institution without understanding that the token represents a claim against a different entity.
A subsidiary structure makes that distinction more explicit. It does not, by itself, settle every question about insolvency, operational dependencies or support from the parent. Those outcomes depend on the legislation, supervisory requirements and contractual arrangements.
The practical takeaway: banks gain a proposed organizational pathway, but the subsidiary’s legal identity and obligations must remain visible to customers.
Federal budget materials are available through the Government of Canada’s budget portal.
2. The Bank Act boundary: issuance is not automatically deposit-taking
Complementary amendments would clarify that issuing stablecoins does not, in itself, constitute deposit-taking under Part XII of the Bank Act.
That is a targeted clarification with implications for bank affiliates and foreign institutions operating in Canada. It addresses how a particular activity is classified; it should not be read as a blanket exemption from financial regulation.
Put simply, a stablecoin can promise a stable Canadian-dollar value without being legally identical to a Canadian-dollar bank deposit. The applicable issuer rules, redemption rights and customer protections still need to be understood on their own terms.
The practical takeaway: clearer classification reduces regulatory ambiguity, but disclosure must prevent customers from confusing a stablecoin with an insured deposit. A bank connection alone does not establish deposit-insurance coverage; the Canada Deposit Insurance Corporation explains its coverage framework here.
3. Reserve custody: an infrastructure opportunity for banks
The Bank of Canada continues developing its supervisory machinery following the release of draft Stablecoin Regulations. Those proposals position domestic banks as potential Canadian-incorporated qualified custodians holding the assets that back regulated stablecoins one-for-one.
This creates an opportunity beyond issuing tokens. A banking group could support the market through reserve custody and related services, even where another business operates the customer-facing stablecoin.
However, a 1:1 backing requirement answers only part of the financial-stability question. The composition, liquidity and legal treatment of reserves also matter, as does the issuer’s ability to meet redemptions during disruption.
The practical takeaway: reserve coverage is essential, but credible redemption arrangements are what make that backing useful to holders under stress.
4. Tokenized deposits: a parallel track, not the same product
The Big Six banks’ joint initiative to build interbank tokenized Canadian-dollar deposit infrastructure reinforces a two-track approach.
- Tokenized deposits represent commercial bank deposit claims in a digital-token format.
- Regulated stablecoins follow a separate issuer-and-reserve framework, with their own legal and redemption arrangements.
Both may support new payment applications. Their shared use of token technology does not make their balance-sheet treatment, customer claims or protections interchangeable.
For professional users evaluating either model, the starting questions should be straightforward: Who owes the money? How is redemption obtained? What happens if the issuer, custodian or payment infrastructure fails?
What to watch next
The next implementation milestones are the final legislative language, subsidiary requirements, custodian eligibility rules and operational standards for reserves and redemption.
This week’s bottom line: Ottawa is making space for digital-money innovation while drawing a firmer boundary around its risks. That is a constructive direction. Its success will depend on making those boundaries work not just in corporate structures and regulatory filings, but also in everyday payments and periods of financial stress.