UK Digital Gilt: Why the HSBC–LSEG Link Is DIGIT’s Real Test
Britain’s digital gilt will test more than blockchain. The HSBC–LSEG link must make ownership, settlement and investor access work across separate platforms. As DIGIT targets issuance in early 2027, discover why legal certainty, cash coordination and operations will matter more than the novelty of putting government debt on a ledger.
Edinburgh, Scotland
Nov 2, 2026
Britain’s first digitally native government bond will test more than whether a gilt can be issued using distributed ledger technology. It will test whether investors can reach the same security through different market infrastructures without introducing new uncertainty over ownership, settlement or operational responsibility.
That is the significance of the connection between HSBC Orion and London Stock Exchange Group at the centre of the government’s Digital Gilt Instrument, or DIGIT. A successful transaction would demonstrate that established institutions can connect digital securities platforms. The more demanding question is whether that connection makes the market easier to use.
In its announcement on the next stage of DIGIT, HM Treasury sets out plans for issuance in the first quarter of 2027 under the Wholesale Financial Markets Digital Strategy. It also names Barclays, HSBC, Lloyds, Morgan Stanley, NatWest and RBC Capital Markets as lead managers, responsible for work including syndication, documentation, bookbuilding and onboarding participants to the digital platform.
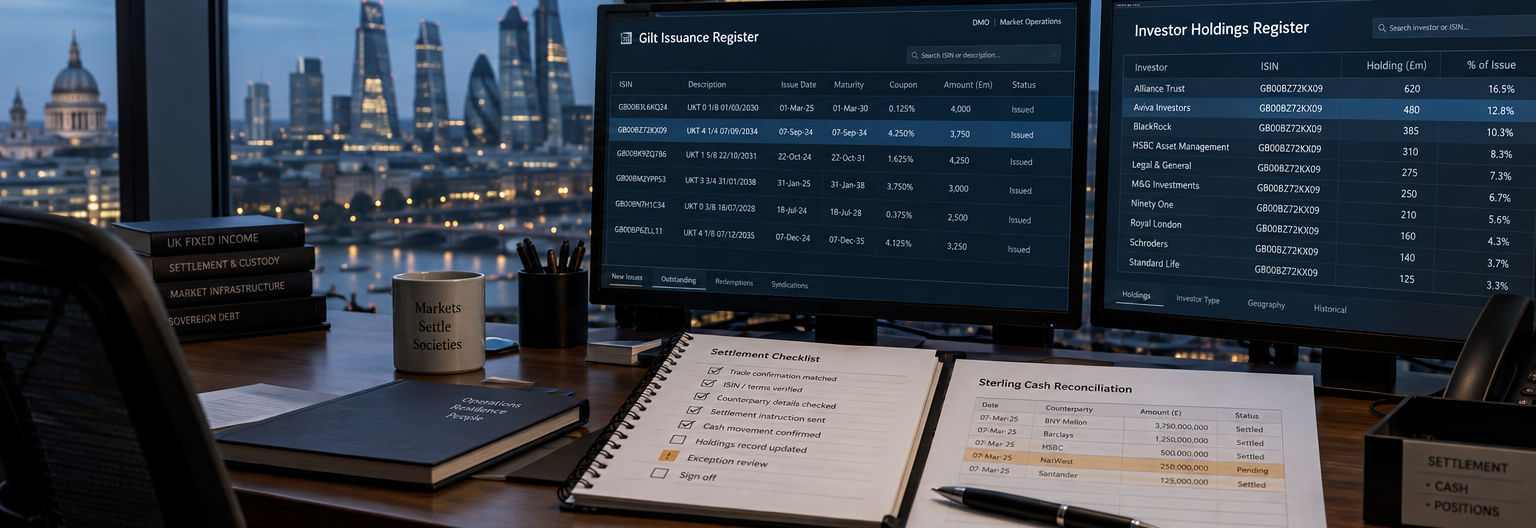
Those appointments provide a familiar institutional framework. Less familiar is the Bank of England-approved bilateral link between two Digital Securities Depositories within the Digital Securities Sandbox: HSBC Orion as issuer DSD and LSEG as investor DSD. The arrangement is intended to support access through multiple venues, secondary-market interoperability and on-chain settlement at issuance.
The distinction matters. Issuing a bond on a digital platform is one achievement; making it accessible beyond that platform is another.
One gilt, different points of access
Digital securities promise more efficient record-keeping and processing, but separate platforms can create their own boundaries. If investors and intermediaries must join each issuer’s chosen infrastructure, the result may be a collection of technically sophisticated markets that remain expensive to connect.
The HSBC–LSEG arrangement addresses that problem through defined institutional roles. One DSD serves the issuance side; the other provides an investor-side connection. The objective is not to require every participant to operate directly on the same platform.
That could prove commercially important. An asset manager’s ability to buy a security depends on more than investment appetite. Its custodian must be able to support the holding, its operational systems must recognise the position, and its controls must accommodate settlement, valuation and reporting. Familiar access arrangements can matter as much as the technology beneath them.
A sovereign issuer offers a useful setting for this experiment. Gilts are established instruments with a developed investor base and an understood credit framework. The pilot can therefore focus attention on the infrastructure, although a successful DIGIT issuance would not by itself demonstrate that the arrangement is ready to accommodate the scale and variety of the wider gilt market.
The ownership question comes first
“Two ledgers, one gilt” is a useful shorthand, but it should not imply two independently authoritative versions of the same security. The operating and legal arrangements must establish how holdings are represented across the infrastructure, which records establish investors’ rights and when a transfer becomes final.
That requires more than passing messages between systems. A transaction could be accepted on one platform while an associated process remains incomplete on another. The infrastructure needs rules for preventing inconsistent positions, identifying exceptions and restoring a reliable record when something goes wrong.
For a custodian or investment manager, those are practical questions. What evidence establishes a holding? When can the buyer treat a transaction as settled? Who must intervene if an instruction fails? And what happens to transactions already in progress when one system becomes unavailable?
Treasury’s announcement establishes the intended functions of the link, rather than providing a complete public operating manual. Regulatory approval within the sandbox is a significant milestone, but it should not be confused with proof of resilience under every trading condition or blanket approval for other platform connections.
A digital bond still needs money
The cash side is equally important. Recording a bond transfer on a ledger does not, by itself, explain how payment is made or how the securities and cash movements are coordinated.
Delivery-versus-payment arrangements are designed to prevent a buyer paying without receiving securities, or a seller delivering without receiving payment. A digital issuance still needs to address that risk. The form of settlement money, its availability and the relationship between payment and securities transfer will help determine the transaction’s practical benefits.
Settlement speed also needs to be judged alongside funding requirements. Faster processing can reduce the time during which counterparties are exposed to one another, but arrangements requiring earlier funding may change participants’ liquidity needs. The relevant measure is the overall settlement outcome, not simply the speed at which a ledger updates.
For institutional investors, a persuasive model would combine reliable settlement with manageable cash requirements and clear operational procedures. “On-chain” describes part of the mechanism; it is not, on its own, a measure of efficiency.
From a working link to a workable market
The bilateral nature of the connection is both its strength and its limitation. Two established infrastructure providers can agree a defined operating model, allocate responsibilities and test a contained set of processes. That is a pragmatic way to begin.
Extending the model is a different undertaking. Additional platforms could bring different participant requirements, technical designs and legal arrangements. If each connection requires extensive bespoke integration, some of the savings from digital issuance could be absorbed by the cost of maintaining the links.
The commercial test is therefore whether DIGIT produces reusable arrangements: consistent transaction information, understandable custody structures, clear liability and procedures that other institutions can adopt without rebuilding their operations around each new issue.
Investors will also need dependable servicing throughout the bond’s life. Interest payments, transfers, reconciliation and redemption must work after the attention surrounding issuance has subsided. A well-executed launch is necessary, but routine administration will provide the more durable evidence of usefulness.
DIGIT’s strongest proposition is not that government borrowing needs a technological reinvention. It is that established financial institutions may be able to use digital infrastructure to reduce specific frictions while preserving the legal certainty and operational discipline on which the gilt market depends.
The HSBC–LSEG link makes that proposition testable. Its value will ultimately be measured less by the presence of two connected platforms than by whether investors can use them without having to manage the gap between them.